Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards
The Fee Comparison Engine for Cash Advances
Not all credit cards charge the same cash advance fee — and the cheapest card depends entirely on how much you withdraw. This calculator compares up to 3 cards side-by-side, finds your cheapest option, and shows the exact amount at which each fee structure changes.
Sachin Ramdurg Certified Quality Champion
Software Engineer & Founder · Credit Algorithms, Compliance & Software Architecture
Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards
Not all credit cards charge the same cash advance fee — and the cheapest card depends entirely on how much you withdraw. This calculator compares up to 3 cards side-by-side, finds your cheapest option, and shows the exact amount at which each fee structure changes.
Card Fee Structures
Typical: 3–5%
Typical: $5–$15
Typical: $3–$5
Typical: 3–5%
Typical: $5–$15
Typical: $3–$5
National Statistics
Key data indicators relevant to the Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards for National.
How to Use theCredit Card Cash Advance Fee Calculator: Compare Fees Across Cards
A comprehensive walkthrough on how to maximize your savings using the free Credit Card Cash Advance Fee Calculator provided by iCreditCalculators. Step-by-step tutorial.
About the Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards
The Credit Card Cash Advance Fee Calculator solves a problem that most consumers never stop to analyse: your cheapest credit card for purchases is not necessarily your cheapest card for a cash advance. Card issuers each set their own fee structure — a combination of a percentage rate and a flat minimum — and the winner changes depending on how much cash you withdraw.
This tool allows you to enter the fee structures of up to three cards side by side, input the advance amount you need, and instantly see which card will cost you the least. You also see the break-even amount for each card — the threshold at which the percentage fee overtakes the flat minimum — giving you strategic knowledge you can use for any future withdrawal.
Unlike most calculators, this tool also incorporates the ATM owner surcharge — the additional $3–$5 fee that the ATM's bank charges separately from your card issuer's transaction fee. This brings the total cost estimate in line with what you will actually see debited from your available credit.
The result is a complete, honest fee comparison that empowers you to make the financially optimal choice in any cash advance scenario, even in an emergency where decision time is short.
Features of the Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards
Multi-Card Fee Comparison
Enter up to 3 cards simultaneously and see their fees compared side-by-side at any advance amount — instantly updated as you adjust the slider.
Best Option Highlight
The calculator automatically identifies and badges the lowest-fee card for your chosen advance amount, removing guesswork from the decision.
Break-Even Analysis
Displays the exact advance amount at which each card switches from flat-fee to percentage-fee dominance — critical context for recurring use.
ATM Surcharge Inclusion
Incorporates the third-party ATM surcharge into the total cost, giving you a realistic figure that matches the amount you will actually be charged.
Effective Rate Display
Calculates the effective fee percentage (total fees ÷ advance amount) for each card — the single most useful comparator across different fee structures.
Savings Callout
Quantifies the exact dollar savings from choosing the cheapest card over the most expensive, making the opportunity cost of a poor card choice tangible.
How does the Calculator Work?
Calculation Process
Set the Advance Amount
Use the slider or quick-select buttons to set the amount of cash you plan to withdraw. The comparison updates instantly.
Enter Each Card's Fee Structure
Check your cardholder agreement for the 'Cash Advance Fee' section. Enter the percentage rate, the flat minimum, and the ATM surcharge for each card.
Add Cards for Comparison
Use the 'Add Card' button to include up to 3 cards. Rename them by clicking the card name label.
Click Compare Fees
The calculator shows each card's breakdown, flags the cheapest option, displays the break-even thresholds, and shows a stacked fee chart.
Why should you use our Calculator?
| Feature | Our Calculator | Others |
|---|---|---|
| Cards Compared | Up to 3 cards simultaneously, side-by-side | Single card only |
| Fee Logic | Correctly applies max(% fee, flat min) — matches your agreement | Often only calculates % fee, understating cost |
| ATM Surcharge | Included as a separate configurable input | Ignored, underestimating real cost |
| Break-Even | Per-card break-even amount shown for strategic use | Not provided |
| Best Option | Automatically highlighted with savings vs. worst option | No recommendation |
| Effective Rate | Shown per card for apple-to-apple comparison | Not shown |
| Privacy | 100% client-side — no data sent anywhere | Requires email or form submission |
| Cost | 100% free | Freemium or ad-heavy |
10 Scenarios: What is the Use of This Calculator Online?
Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards Scenarios
| Scenario | Action Taken | Impact | Result |
|---|---|---|---|
| Small $100 Advance | Card A: 5%/$10 min vs Card B: 3%/$15 min | Card A: $13.50 total | Card B: $18.50 total | Card A is 26% cheaper — flat fee dominates both |
| $500 Advance | Card A: 5%/$10 min vs Card B: 3%/$15 min | Card A: $28.50 | Card B: $30.00 | Card A still slightly cheaper; % fee now active on Card A |
| $800 Advance | Card A: 5%/$10 min vs Card B: 3%/$15 min | Card A: $43.50 | Card B: $27.50 | Card B becomes 37% cheaper above the crossover point |
| Low-Fee ATM Hunt | Same card, ATM surcharge $0 vs $5 | $0 surcharge saves $5 instantly on any advance | Always use bank-network ATMs to avoid ATM owner surcharges |
| International ATM | Foreign ATM adds $5 surcharge + currency conversion fee | Total fee for $500 can reach 12–14% of amount | Use pre-loaded travel cards or local cash alternatives abroad |
| Same Rate, Different Minimum | 5%/$5 min vs 5%/$15 min — $100 advance | Card 1: $8.50 | Card 2: $18.50 — same APR structure | $10 savings just from choosing lower minimum card |
| Premium Card Comparison | Premium travel card: 5%/$20 min vs Standard: 3%/$10 | For $200 advance: Premium $23.50 vs Standard $16.00 | Premium cards are often worse for cash advances — check before using |
| Emergency Benchmark | Best available card vs typical payday loan at 400% APR | Cash advance fee-only cost: 3–7% | Payday: 15–25% for 14 days | Card advance is cheaper than payday lending even with high fees |
Case Studies: Real World Success Stories
The Wrong Card for the Right Amount
Situation
Sarah had two cards — one with a 5%/$10 fee and one with a 3%/$15 fee. She instinctively used the '3%' card for a $200 advance, assuming lower percentage = lower cost.
Outcome
Calculator showed her 3% card cost $18.50 (flat fee active) vs $13.50 on the 5% card — she paid $5 more for no reason.
The ATM Owner Surprise
Situation
Marcus calculated his expected cash advance fee at $25 and budgeted accordingly. He used an out-of-network ATM at a convenience store.
Outcome
The ATM charged a $4.99 surcharge, bringing his total to $29.99 — almost 20% more than expected.
The Break-Even Strategy
Situation
David needed approximately $300–$400 depending on what the ATM offered. His two cards had different break-even points: $300 vs $500.
Outcome
Calculator showed the break-even for Card A was $300, meaning above $300 Card B was cheaper. He withdrew $350 with Card B and saved $4.
The Emergency Fund Replacement
Situation
A family used cash advances repeatedly over 3 months as an informal emergency fund.
Outcome
Calculator showed they paid $187 in fees plus $340 in interest — $527 for repeated $500 advances they could have gotten from a $1,000 emergency savings account.
Advantages and Risks
Advantages
- Instant access to cash at any ATM, no application or approval process.
- Available globally — useful in countries where cards are not accepted for purchases.
- Different cards have different fee structures — smart comparison can meaningfully reduce costs.
- Fee-only cost (without interest) is significantly lower than payday loan rates for genuinely short repayment periods.
- This calculator turns a often impulsive decision into an informed, quantified one.
Disadvantages & Risks
- Card fees (% + flat) are charged immediately, even if the advance is repaid the same day.
- ATM surcharges add a third-party cost beyond the card issuer's control that many consumers overlook.
- Premium and travel rewards cards often have higher cash advance fees, making them poor choices for ATM withdrawals.
- The variety of fee structures across cards makes it easy to use the wrong card by default.
- Frequent use of cash advances typically signals cash flow problems that fees and interest will worsen.
Risks & Mitigation Strategies
Comprehensive Guide to Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards
How Cash Advance Fees Actually Work: A Fee-First Analysis
The confusion around cash advance fees stems from their two-part structure: a percentage of the advance and a flat minimum. Your card charges whichever is higher — meaning the fee calculation is dynamic depending on your withdrawal amount.
The Break-Even Concept. Given a card with a 5% fee and a $10 flat minimum, the break-even point is $200 (5% of $200 = $10). Below $200, the flat minimum dominates. Above $200, the percentage takes over. Every card has its own break-even point, and knowing these thresholds lets you select the right card for any withdrawal amount.
Why ATM Owner Surcharges Matter. Your card issuer's fee is one thing — but the ATM owner (often a different bank) can charge an independent surcharge. This fee appears as a separate line-item and is commonly $3–$5 at out-of-network machines and up to $8–$10 at tourist and casino ATMs. It's charged on top of your card's fee and begins accruing interest immediately as part of the advance total.
The Strategic Decision Framework. (1) Determine your exact advance amount. (2) Use this calculator to compare all your eligible cards at that amount. (3) Choose the card with the lowest total fee. (4) Use an in-network ATM to avoid the owner surcharge. (5) Repay the advance as soon as possible to minimize interest exposure.
Key Takeaways
- Cash advance fees are the greater of: a percentage (3–5%) OR a flat minimum ($5–$15) — whichever costs more.
- For small advances, the flat minimum dominates — making small withdrawals disproportionately expensive.
- ATM surcharges (charged by the ATM owner, not your card issuer) add $3–$5 on top of the card fee.
- The break-even amount is where the percentage fee exactly equals the flat minimum — it shifts with every card.
- A card with a lower % fee but higher flat minimum may be cheaper for large advances and more expensive for small ones.
- Comparing fees across cards before withdrawing can save real money — especially on larger advances.
- The effective fee rate (total fees ÷ advance amount) is the most useful single number for comparing options.
Frequently Asked Questions
Was this Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards helpful?
Your feedback helps us improve our free tools.
Research & Development Support By: Vijayalaxmi Umachagi
CA, Legal, Financial Expert & Co-Founder
Vijayalaxmi Umachagi is a CA practitioner and financial expert by passion and an entrepreneur. She has 10+ years of Commerce, MCom and professional experience across finance and human resources who help developers build financial tools.
Built & Engineered By: Sachin Ramdurg
Software Engineer & Founder
Sachin Ramdurg is a software engineer by passion and an entrepreneur. He has 15+ years of engineering and professional experience across multiple domains, building accurate, high-performance financial tools and complex algorithms to make them accessible to everyone.
Community Insights
Real experiences and strategies from users of the Credit Card Cash Advance Fee Calculator: Compare Fees Across Cards.
Share Your Insight
Sam
"Really easy to use. I was confused about {topic}, but the charts made it so clear."
Carlos M.
"This {calc} was exactly what I needed. It helped me realize I could save thousands."
Jenny
"Saved me from making a bad financial decision. Highly recommend!"
Alex
"The 10 scenarios section really opened my eyes. Thanks for building this {calc}."
What to Do Next?
Based on your analysis with the Credit Card Cash Advance Fee Calculator, these tools will help you execute the next phase of your financial plan.
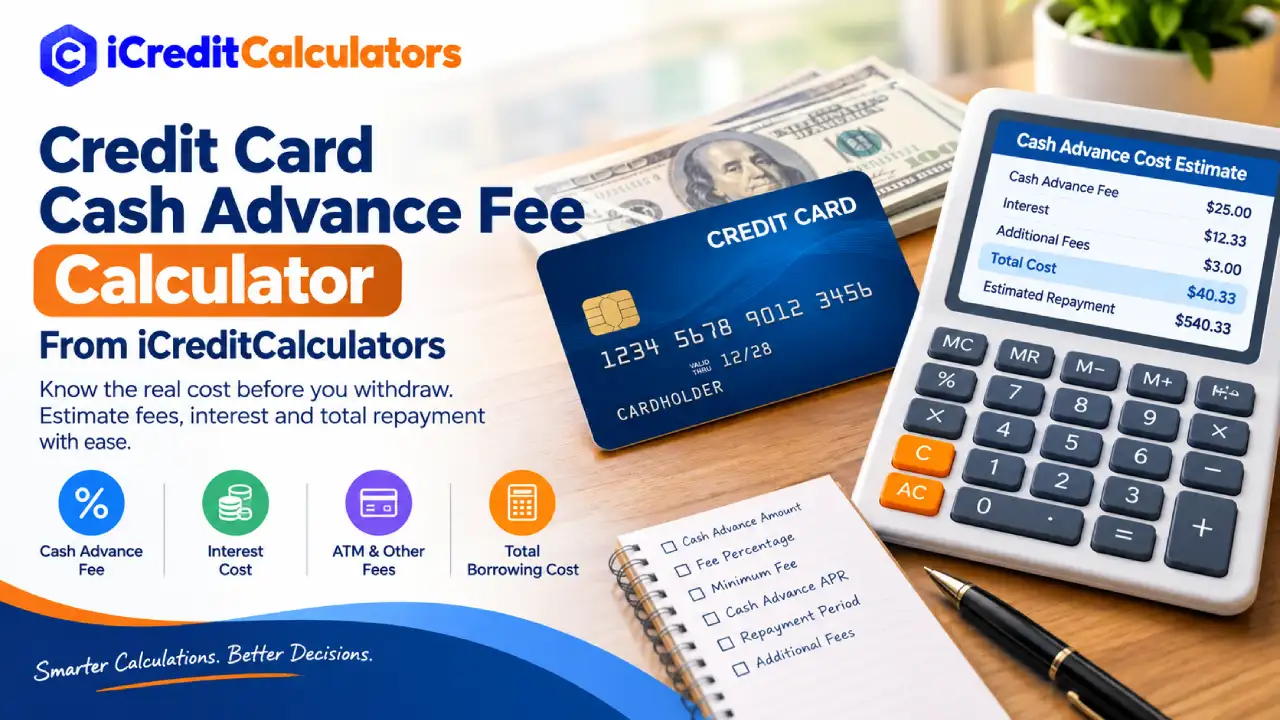
Credit Card Cash Advance Fee Calculator From iCreditCalculators
Credit Card Cash Advance Fee Calculator From iCreditCalculators
A credit card cash advance can look like a quick way to get cash when you need it, but the actual cost can be higher than the amount you withdraw because you may pay a cash advance fee, interest, and ATM or other transaction fees.
If you want to understand how to estimate the total cost of borrowing cash using your credit card, the Credit Card Cash Advance Fee Calculator from iCreditCalculators can help you estimate these costs before you take the advance. This guide explains how cash advance fees work, how interest can add to the balance, which numbers you need from your credit card agreement, and how to use the calculator to make a clearer borrowing decision.
About the Credit Card Cash Advance Fee Calculator
The Credit Card Cash Advance Fee Calculator from iCreditCalculators is designed to help you estimate the cost of taking cash from a credit card. Instead of looking only at the amount you receive from an ATM or another cash-advance method, the calculator helps you consider the fee charged by the card issuer and the interest that may build up while the cash advance remains unpaid.
This matters because a cash advance is different from an ordinary credit card purchase. The Consumer Financial Protection Bureau (CFPB) explains that cash advances can involve additional fees and interest, and interest commonly begins when the cash is withdrawn rather than after a normal purchase grace period. (Consumer Financial Protection Bureau)
For example, suppose you withdraw $500 and your card charges a 5% cash advance fee. The fee would be $25. If the cash advance also carries a 30% APR, the borrowing cost does not stop at that $25 fee. Interest can continue to accumulate until the balance is paid.
The calculator is therefore useful for looking at the full short-term borrowing cost, rather than focusing only on the cash received.
Quick answer: A credit card cash advance usually has two major costs to check: the cash advance fee and the cash advance interest. Some cards may also charge an ATM fee or another transaction-related charge. Your card agreement determines the exact amounts.
The CFPB maintains a database of credit card agreements that includes information about cash advance fees and interest terms. However, your own card agreement and current statement are the best sources for your account-specific terms. (Consumer Financial Protection Bureau)
What Is a Credit Card Cash Advance?
A credit card cash advance is a way of borrowing money against your available credit limit instead of using your card for a normal purchase.
The most familiar example is using a credit card at an ATM to withdraw cash. However, a cash advance can cover more than an ATM withdrawal. Depending on the card agreement, transactions involving cash equivalents or certain other services can also be treated as cash advances.
The CFPB's credit card definitions include examples such as ATM cash withdrawals, wire transfers, foreign currency, money orders, lottery tickets, gambling-related transactions, and cash access checks. The exact treatment can vary by card issuer and transaction. (Consumer Financial Protection Bureau)
This distinction is important because a transaction that feels like a normal purchase to the cardholder may be classified differently by the issuer.
Cash Advance vs. Regular Credit Card Purchase
A regular purchase and a cash advance can have very different costs.
With a normal purchase, your card may provide a grace period if you meet the terms of your account. With a cash advance, interest commonly starts accruing immediately. The CFPB specifically notes that cash advance interest generally starts when you withdraw the money. (Consumer Financial Protection Bureau)
A simple comparison looks like this:
| Feature | Regular Purchase | Cash Advance |
|---|---|---|
| Uses available credit | Yes | Yes |
| May have a separate APR | Usually | Often |
| Cash advance fee | No | Often |
| Interest may start immediately | Usually not under a qualifying grace period | Commonly yes |
| ATM fee possible | No | Yes |
| Cash received directly | No | Yes |
This is why the cash advance APR and cash advance fee should be checked before withdrawing money.
Why Cash Advances Can Become Expensive
The main problem with a cash advance is that several costs can apply at the same time.
You may have:
- The amount of cash withdrawn
- A cash advance transaction fee
- Interest charged on the cash advance balance
- An ATM fee
- Other fees depending on the transaction and card agreement
The CFPB reported that major credit card issuers charged consumers $717 million in cash advance fees on $3.6 billion in cash advance volume during 2022. That works out to an average fee of about $1 for every $19 in cash advance volume across the data examined. (Consumer Financial Protection Bureau)
The same CFPB analysis found that, among agreements from seven major issuers it reviewed, most used a fee structure based on the greater of a dollar minimum or a percentage of the transaction, with "greater of $10 or 5%" being common in that review. This does not mean every credit card uses those terms. Your own agreement controls. (Consumer Financial Protection Bureau)
For smaller withdrawals, a minimum fee can have a particularly large effect.
For example:
- Cash advance: $100
- Fee: 5%
- Percentage fee: $5
- Minimum fee: $10
- Actual fee: $10
The $10 fee is effectively 10% of the $100 withdrawn, before adding any interest.
That is one reason the calculator can be useful even when the amount borrowed seems small.
Credit Card Cash Advance Fee Formula
The first calculation is the cash advance fee itself.
A simple percentage-based fee can be calculated as:
Cash Advance Fee = Cash Advance Amount × Cash Advance Fee Rate
For example, if you withdraw $1,000 and the card charges a 5% fee:
Cash Advance Fee = $1,000 × 5%
Cash Advance Fee = $50
However, many cards use a minimum fee. In that situation, the actual calculation may be:
Cash Advance Fee = Greater of (Cash Advance Amount × Fee Rate) or Minimum Fee
Suppose the card charges 5% or $10, whichever is greater.
For a $100 advance:
Percentage fee = $100 × 5% = $5
Minimum fee = $10
Actual cash advance fee = $10
For a $1,000 advance:
Percentage fee = $1,000 × 5% = $50
Minimum fee = $10
Actual cash advance fee = $50
This type of minimum-fee structure is important because the same percentage cannot be used blindly for every transaction.
Formula Abbreviations
| Term | Meaning |
|---|---|
| Cash Advance Amount | Amount of cash withdrawn from the credit card |
| Cash Advance Fee Rate | Percentage charged by the card issuer |
| Minimum Fee | Lowest cash advance fee charged under the card's terms |
| Cash Advance Fee | Fee added because you used the card for a cash advance |
The CFPB's credit-card data dictionary also recognizes several possible cash advance fee structures, including dollar fees, percentage fees, minimum dollar amounts, and other calculation methods. (Consumer Financial Protection Bureau)
Cash Advance Interest Formula
The cash advance fee is only part of the cost.
You also need to consider the interest charged on the cash advance balance.
For a simple daily estimate, you can convert the annual percentage rate into a daily rate:
Daily Interest Rate = Cash Advance APR ÷ 365
Then:
Daily Interest = Cash Advance Balance × Daily Interest Rate
And for a basic estimate over a number of days:
Estimated Interest = Cash Advance Balance × (Cash Advance APR ÷ 365) × Number of Days
For example, suppose:
- Cash advance = $500
- Cash advance APR = 30%
- Time outstanding = 30 days
The estimated interest would be:
Estimated Interest = $500 × (30% ÷ 365) × 30
Estimated Interest ≈ $12.33
If the cash advance fee is $25, the basic estimated borrowing cost becomes:
Total Cost = $25 + $12.33
Total Cost ≈ $37.33
The calculation above is a simplified estimate. Actual credit card interest can depend on the issuer's balance calculation method, transaction posting date, payments, billing-cycle timing, and other account terms.
The Federal Reserve's Regulation Z rules require issuers to disclose applicable APRs and cash advance fees, while card agreements explain how balances and finance charges are calculated. (Federal Reserve)
Formula for Total Cash Advance Cost
For a straightforward calculator estimate, the overall cost can be represented as:
Total Cash Advance Cost = Cash Advance Fee + Estimated Interest + Additional Fees
If there is an ATM fee, for example:
Total Cash Advance Cost = Cash Advance Fee + Estimated Interest + ATM Fee
And the approximate amount you repay would be:
Total Repayment Amount = Cash Received + Total Cash Advance Cost
Consider this example:
- Cash received = $800
- Cash advance fee = $40
- Estimated interest = $20
- ATM fee = $3
Then:
Total Cash Advance Cost = $40 + $20 + $3
Total Cash Advance Cost = $63
And:
Total Repayment Amount = $800 + $63
Total Repayment Amount = $863
This makes the cost easier to understand. You did not simply borrow $800. Under these assumptions, you would need approximately $863 to cover the original cash and the estimated additional charges.
How the Credit Card Cash Advance Fee Calculator Works
The calculator takes the major variables that affect a cash advance and turns them into an estimated cost.
The most important inputs are generally:
- Cash advance amount
- Cash advance fee percentage
- Minimum cash advance fee, if applicable
- Cash advance APR
- Number of days the balance remains unpaid
- Additional ATM or transaction fee, where applicable
The calculator then applies the relevant formulas to estimate the fee and interest.
The result can help you answer questions such as:
- How much will my cash advance fee be?
- How much interest could I pay?
- What will a $500 cash advance really cost?
- How much would I repay after 30 days?
- Does a minimum cash advance fee make a small withdrawal expensive?
- How does a 5% fee compare with a flat fee?
- How much does the cost increase if I wait longer to repay?
The calculator does not change your card's terms. Instead, it uses the information you provide to create an estimate.
That distinction is important because credit card terms vary between issuers and products. The CFPB's credit card agreement database shows that cash advance fee structures and APRs can differ across agreements. (Consumer Financial Protection Bureau)
How to Use the Credit Card Cash Advance Fee Calculator
Using the calculator should be straightforward, but the accuracy of the result depends heavily on entering the correct information.
Step-by-Step Instructions
Step 1: Enter the cash advance amount
Enter the amount you plan to withdraw.
For example:
Cash Advance Amount = $500
Use the amount you actually expect to take as a cash advance rather than your overall credit limit.
Step 2: Enter the cash advance fee
Check your credit card agreement or pricing disclosure for the cash advance fee.
For example:
Cash Advance Fee = 5%
If your agreement says "$10 or 5%, whichever is greater," you should also enter the applicable minimum fee.
Step 3: Enter the minimum fee
If your card has a minimum cash advance fee, enter it.
Example:
Minimum Fee = $10
The calculator can then account for the minimum when determining the actual transaction fee.
Step 4: Enter the cash advance APR
Look at your credit card statement or card agreement for the APR for cash advances.
Do not automatically use your purchase APR.
A card can have separate APRs for purchases, balance transfers, and cash advances. The CFPB notes that statements must identify balances associated with different APR categories when applicable. (Consumer Financial Protection Bureau)
Step 5: Enter the number of days
Enter the estimated number of days the cash advance will remain outstanding.
For example:
Days = 30
If you expect to repay the balance sooner, use the expected number of days rather than automatically entering 30.
Step 6: Include an ATM fee if applicable
If the ATM operator charges a separate fee, include it in the appropriate field if the calculator provides one.
The CFPB warns that an ATM fee may be added to the costs associated with a credit card cash advance. (Consumer Financial Protection Bureau)
Step 7: Review the estimated total
After entering the information, review the estimated:
- Cash advance fee
- Interest cost
- Additional fees
- Total cash advance cost
- Estimated repayment amount
This gives you a clearer picture of the borrowing cost before you proceed.
Example: $500 Cash Advance With a 5% Fee
Suppose you need $500 in cash.
Your card terms are assumed to be:
- Cash advance amount: $500
- Cash advance fee: 5%
- Minimum fee: $10
- Cash advance APR: 30%
- Repayment period: 30 days
- ATM fee: $0
First, calculate the percentage fee:
$500 × 5% = $25
Because $25 is greater than the $10 minimum:
Cash Advance Fee = $25
Next, estimate 30 days of interest:
$500 × (30% ÷ 365) × 30 ≈ $12.33
Then:
Total Estimated Cost = $25 + $12.33
Total Estimated Cost ≈ $37.33
So the estimated amount required to repay the $500 advance after 30 days would be approximately:
$500 + $37.33 = $537.33
This example shows why looking only at the $500 withdrawal can give an incomplete picture.
A Small Cash Advance Can Have a Large Effective Cost
Minimum fees become especially important when the amount borrowed is small.
Imagine a card that charges 5% or $10, whichever is greater.
If you withdraw $50:
5% of $50 = $2.50
But the minimum is $10.
Therefore:
Actual Fee = $10
The fee alone equals:
$10 ÷ $50 = 20%
So before interest is added, the fee represents 20% of the cash received.
Now consider a $1,000 withdrawal:
5% of $1,000 = $50
The $50 fee is only 5% of the amount withdrawn.
This demonstrates an important point: the same card fee structure can have a very different impact depending on the withdrawal amount.
The CFPB has specifically highlighted the high cost of minimum fees for smaller cash advances. (Consumer Financial Protection Bureau)
What Information Should You Check Before Using the Calculator?
Before entering numbers, find the actual terms for your card.
Look for:
- Cash advance APR
- Cash advance fee
- Minimum cash advance fee
- ATM fees
- Cash advance limit
- Balance calculation method
- Payment allocation rules
- Any minimum interest charge
- Any special transaction rules
Your card agreement is particularly important because the same type of credit card transaction can have different pricing depending on the issuer.
The CFPB says consumers can use its credit card agreement database to review general agreements, while account-specific questions should be directed to the card issuer. (Consumer Financial Protection Bureau)
For example, one agreement may charge 5% with a $10 minimum, while another agreement may use a different percentage and minimum. CFPB agreement records show examples of both 3% and 5% cash advance structures, illustrating why you should not assume that one fee applies to every card. (Consumer Financial Protection Bureau)
Do Not Assume Your Purchase APR Is the Cash Advance APR
This is one of the most common mistakes when estimating the cost.
Suppose your card shows:
- Purchase APR = 24%
- Cash advance APR = 30%
Using 24% in the cash advance calculation would underestimate the interest.
Your calculator input should use the cash advance APR, not the purchase APR.
The CFPB explains that credit cards can have different interest rates for purchases, cash advances, and other balance categories. (Consumer Financial Protection Bureau)
How the Credit Card Cash Advance Fee Calculator Helps
A cash advance calculation becomes much more useful when you look beyond the initial fee. The Credit Card Cash Advance Fee Calculator from iCreditCalculators brings the main cost factors together so you can estimate what borrowing cash through your credit card may actually cost.
The calculator is especially helpful when you are comparing different withdrawal amounts or different repayment periods. A $500 cash advance repaid quickly can have a very different cost from the same $500 balance carried for several weeks or months.
Cash advances are generally more expensive than ordinary purchases because they commonly have a separate, often higher APR and typically begin accruing interest from the transaction date. The CFPB also notes that cash advances may include a separate fee and potentially an ATM fee. (Consumer Financial Protection Bureau)
What the Calculator Can Show
Depending on the inputs available on the calculator, you can use it to estimate:
- Cash advance fee
- Estimated interest
- Additional transaction or ATM fees
- Total estimated borrowing cost
- Estimated amount to repay
- Effect of a higher or lower cash advance amount
- Effect of keeping the balance outstanding longer
This makes the calculator useful for planning rather than simply calculating a percentage.
For example, if you are deciding between withdrawing $200 and $500, you can enter both amounts separately and compare the estimated costs. This can make the effect of a minimum cash advance fee much easier to see.
Important Factors That Affect Cash Advance Cost
Several variables can change the final cost of a cash advance.
1. Cash Advance Amount
The amount you withdraw is the starting point.
A larger withdrawal generally produces a larger percentage-based fee and more interest dollars when the APR and repayment period remain unchanged.
For example:
- $200 withdrawal at 5% = $10
- $500 withdrawal at 5% = $25
- $1,000 withdrawal at 5% = $50
But if the card has a $10 minimum fee, a $100 withdrawal would not produce a $5 fee. The minimum would apply instead.
2. Cash Advance Fee
The card issuer determines the cash advance fee under the terms of the account.
Some agreements use a percentage. Others may use a percentage subject to a minimum dollar amount. Federal disclosure rules require applicable cash advance fees to be disclosed to consumers. (Federal Reserve)
A fee that looks small can become meaningful when the withdrawal is small.
3. Cash Advance APR
The APR is one of the most important numbers in the calculation.
The Federal Reserve's Regulation Z rules require applicable APRs for different transaction categories, including cash advances, to be disclosed. (Federal Reserve)
Do not assume that the APR shown for purchases is the rate used for a cash advance.
4. Repayment Time
Time matters because interest can continue to accumulate.
Consider two otherwise identical $500 cash advances:
- One is repaid after 10 days.
- The other remains outstanding for 60 days.
The second transaction has more time to accumulate interest.
This is why entering an expected repayment period into the calculator can make the estimate more useful than calculating the transaction fee alone.
5. ATM or Other Fees
An ATM operator may charge a separate fee when you use an ATM for a credit card cash advance. The CFPB specifically advises consumers to consider possible ATM fees in addition to the card issuer's fees and interest. (Consumer Financial Protection Bureau)
This means the issuer's cash advance fee is not necessarily the only fee connected to the transaction.
Why Our Calculator Is Useful
The goal of a calculator should not be to make a financial decision for you. Its purpose is to make the numbers easier to understand.
The Credit Card Cash Advance Fee Calculator from iCreditCalculators can help put several costs into one calculation instead of requiring you to work through separate calculations manually.
Clear Cost Breakdown
Rather than seeing only the amount withdrawn, you can break the transaction into:
Cash received → cash advance fee → interest → additional fees → estimated total cost
This structure makes the result easier to understand.
Quick What-If Calculations
You can change one input and see how the estimated result changes.
For example, you could compare:
- $300 for 15 days
- $300 for 30 days
- $300 for 60 days
You could also compare a 25% APR with a 30% APR or test a 3% fee against a 5% fee.
Useful for Short-Term Planning
A cash advance is often considered because someone needs money quickly.
The calculator lets you estimate the cost before taking the cash advance, which gives you a chance to review the numbers instead of discovering the full cost after the transaction appears on your statement.
Why Use a Calculator Instead of Doing the Math Manually?
You can certainly calculate a cash advance fee with a calculator app or spreadsheet.
The challenge is that the transaction can involve more than one calculation.
You may need to determine the percentage fee, compare it with a minimum fee, convert the APR into a daily rate, estimate interest for the number of days outstanding, and then add any other applicable costs.
For example, assume:
- Cash advance = $750
- Fee = 5%
- Minimum fee = $10
- APR = 30%
- Days = 45
- ATM fee = $3
The fee calculation is:
$750 × 5% = $37.50
The minimum does not apply because $37.50 is greater than $10.
The simplified interest estimate is:
$750 × (30% ÷ 365) × 45 ≈ $27.74
Then:
Estimated Total Cost = $37.50 + $27.74 + $3
Estimated Total Cost ≈ $68.24
The approximate repayment amount would therefore be:
$750 + $68.24 = $818.24
A calculator makes these repeated comparisons easier, particularly when you want to test several scenarios.
10 Credit Card Cash Advance Examples
The following examples use hypothetical card terms for illustration. They are not a representation of the terms of every US credit card.
For the examples below, the simplified interest estimate uses:
Estimated Interest = Cash Advance Amount × (APR ÷ 365) × Days
Actual issuer calculations can differ based on the card agreement and the method used to calculate finance charges.
Example 1: $100 Cash Advance
Assume:
- Cash advance = $100
- Fee = 5%
- Minimum fee = $10
- APR = 30%
- Time = 30 days
- ATM fee = $0
Percentage fee:
$100 × 5% = $5
Because the minimum is $10:
Cash Advance Fee = $10
Estimated interest:
$100 × (30% ÷ 365) × 30 ≈ $2.47
Total estimated cost:
$10 + $2.47 = $12.47
Estimated repayment:
$100 + $12.47 = $112.47
This example demonstrates why minimum fees can matter significantly for small withdrawals.
Example 2: $200 Cash Advance
Assume the same 5% fee, $10 minimum, 30% APR, and 30-day period.
Percentage fee:
$200 × 5% = $10
Estimated interest:
$200 × (30% ÷ 365) × 30 ≈ $4.93
Total estimated cost:
$10 + $4.93 = $14.93
Estimated repayment:
$214.93
At this amount, the 5% percentage fee happens to equal the $10 minimum.
Example 3: $500 Cash Advance
Assume:
- Cash advance = $500
- Fee = 5%
- Minimum = $10
- APR = 30%
- Days = 30
Fee:
$500 × 5% = $25
Interest:
$500 × (30% ÷ 365) × 30 ≈ $12.33
Total estimated cost:
$25 + $12.33 = $37.33
Estimated repayment:
$537.33
The CFPB has used a $400 cash advance at a 30% APR as an illustration and reported approximately $10 of interest over one month, in addition to a $20 cash advance fee under the example terms. (Consumer Financial Protection Bureau)
Example 4: $1,000 Cash Advance
Now assume:
- Cash advance = $1,000
- Fee = 5%
- APR = 30%
- Days = 30
Fee:
$1,000 × 5% = $50
Interest:
$1,000 × (30% ÷ 365) × 30 ≈ $24.66
Total estimated cost:
$50 + $24.66 = $74.66
Estimated repayment:
$1,074.66
Here, the minimum fee has no effect because the percentage calculation is already much higher than $10.
Example 5: $300 Cash Advance for 60 Days
Consider the effect of keeping the same amount outstanding longer.
Assume:
- Cash advance = $300
- Fee = 5%
- Minimum = $10
- APR = 30%
- Days = 60
Fee:
$300 × 5% = $15
Estimated interest:
$300 × (30% ÷ 365) × 60 ≈ $14.79
Total estimated cost:
$15 + $14.79 = $29.79
Estimated repayment:
$329.79
The important difference here is the repayment period. The $300 withdrawal has not changed, but the estimated interest is higher because the balance remains outstanding longer.
Example 6: $750 Cash Advance With an ATM Fee
Assume:
- Cash advance = $750
- Fee = 5%
- Minimum = $10
- APR = 30%
- Days = 45
- ATM fee = $3
Cash advance fee:
$750 × 5% = $37.50
Estimated interest:
$750 × (30% ÷ 365) × 45 ≈ $27.74
Additional ATM fee:
$3
Total estimated cost:
$37.50 + $27.74 + $3 = $68.24
Estimated repayment:
$818.24
This example shows why it is useful to consider the ATM fee separately from the credit card's cash advance fee.
Example 7: $400 Cash Advance at a 25% APR
Now change the APR while keeping the cash advance amount the same.
Assume:
- Cash advance = $400
- Fee = 5%
- APR = 25%
- Days = 30
- Minimum = $10
Fee:
$400 × 5% = $20
Interest:
$400 × (25% ÷ 365) × 30 ≈ $8.22
Total estimated cost:
$20 + $8.22 = $28.22
Estimated repayment:
$428.22
This demonstrates why the APR is an important calculator input. A lower APR reduces the estimated interest when all other assumptions remain unchanged.
Example 8: $600 Cash Advance for 90 Days
Assume:
- Cash advance = $600
- Fee = 5%
- APR = 30%
- Days = 90
- Minimum = $10
Fee:
$600 × 5% = $30
Estimated interest:
$600 × (30% ÷ 365) × 90 ≈ $44.38
Total estimated cost:
$30 + $44.38 = $74.38
Estimated repayment:
$674.38
The longer repayment period has a noticeable effect on interest.
This is one reason the calculator should not be used only to answer "What is my cash advance fee?" It can also help answer "What could this cash advance cost if I cannot repay it quickly?"
Example 9: $50 Cash Advance With a $10 Minimum Fee
Consider a very small withdrawal.
Assume:
- Cash advance = $50
- Fee = 5%
- Minimum = $10
- APR = 30%
- Days = 30
Percentage fee:
$50 × 5% = $2.50
Minimum fee:
$10
Actual fee:
$10
Interest:
$50 × (30% ÷ 365) × 30 ≈ $1.23
Total estimated cost:
$10 + $1.23 = $11.23
Estimated repayment:
$61.23
The fee alone represents 20% of the $50 withdrawal. This illustrates why minimum fees can have a much larger proportional effect on small cash advances. CFPB research similarly found that minimum cash advance fees can make smaller transactions particularly expensive. (Consumer Financial Protection Bureau)
Example 10: Comparing 15 Days and 60 Days
Suppose you take a $500 cash advance at a 5% fee and 30% APR.
The fee remains:
$500 × 5% = $25
For 15 days:
$500 × (30% ÷ 365) × 15 ≈ $6.16
Estimated total cost:
$25 + $6.16 = $31.16
For 60 days:
$500 × (30% ÷ 365) × 60 ≈ $24.66
Estimated total cost:
$25 + $24.66 = $49.66
The fee does not change, but the estimated interest increases as the balance remains outstanding.
This is an important reason to include days outstanding when using a cash advance calculator.
What These Examples Tell You
The 10 examples reveal several patterns.
First, minimum fees matter most for smaller withdrawals. A $10 minimum is a much larger percentage of a $50 withdrawal than of a $1,000 withdrawal.
Second, time affects interest. If the cash advance balance remains unpaid longer, the estimated interest generally increases.
Third, APR matters. A higher cash advance APR produces a higher interest estimate when the balance and time period remain the same.
Fourth, additional fees can increase the cost. An ATM fee may look small, but it still adds to the overall transaction cost.
Finally, the cash advance fee and interest should be viewed together. Looking at only one number can make the borrowing cost appear lower than the complete estimate.
The CFPB's research reinforces this point: cash advances generally have higher APRs than purchases and usually do not receive the same type of grace period, so interest can begin when the advance is taken. (Consumer Financial Protection Bureau)
Cash Advance Cost vs. Cash Received
It helps to separate cash received from cost of borrowing.
If you withdraw $500 and incur $37.33 in estimated fees and interest, you have received $500 but the estimated cost of obtaining that cash is $37.33.
Therefore:
Cash Received = $500
Estimated Borrowing Cost = $37.33
Estimated Amount Repaid = $537.33
This distinction makes financial calculations much easier to understand.
A cash advance is not free access to your existing money. It is borrowing against your credit line, and the associated charges can reduce the value of the cash you receive.
Why Your Actual Statement May Differ From the Calculator
A calculator provides an estimate based on the information entered. It should not be treated as an exact prediction of your statement balance in every situation.
The actual amount can differ because your credit card issuer may use specific methods for determining finance charges, including the way balances and daily rates are calculated.
Your card agreement may also include:
- Different transaction dates
- Different posting dates
- Variable APR terms
- Minimum interest charges
- Specific payment allocation rules
- Different cash advance limits
- Additional transaction fees
Federal credit card rules require relevant account terms and finance-charge information to be disclosed, but the specific calculation still depends on the card agreement. (Federal Reserve)
For this reason, use the calculator to estimate and compare scenarios, then check your actual credit card agreement for the precise terms.
What Makes iCreditCalculators Different for This Calculation?
The main value of a dedicated calculator is convenience and clarity.
Instead of finding a separate formula for the cash advance fee, another calculation for interest, and another method for adding fees, you can use one calculation framework to examine the transaction.
The calculator is particularly useful for people who want a quick answer before making a financial decision.
It can also help readers understand the relationship between:
Amount borrowed + fee + APR + time + additional charges = estimated borrowing cost
That relationship is more useful than simply memorizing one cash advance fee percentage because card terms can differ.
The CFPB's research shows that cash advance fees vary and that many agreements use minimum-or-percentage structures. (Consumer Financial Protection Bureau)
A Simple Way to Think About the Calculator
If you remember only one concept from this guide, remember this:
A cash advance does not necessarily cost only the amount shown as the cash advance fee.
The total cost can include the fee, interest, and other applicable charges.
The calculator helps turn those separate costs into a single estimate that is easier to understand.
For example:
$500 cash advance + $25 fee + $12.33 estimated interest = approximately $37.33 in borrowing cost
That is the number that matters when comparing the cash advance with other available ways of obtaining money.
How to Read Your Cash Advance Calculator Results
Once you enter your cash advance amount, fee, APR, repayment period, and any additional charges, the result should be viewed as an estimate of the borrowing cost rather than simply a fee number.
The most useful way to read the result is to separate the amount you receive from the additional amount you may have to pay.
For example, if you receive $800 and the estimated additional cost is $63, the important numbers are:
- Cash received: $800
- Estimated additional cost: $63
- Estimated repayment: $863
This makes it easier to understand what the transaction is actually costing you.
Look at the Fee and Interest Separately
The cash advance fee is usually charged because you are using the card to obtain cash.
Interest is different. It is the financing cost associated with carrying the cash advance balance.
For example:
Cash Advance Fee = $40
Estimated Interest = $20
Estimated Additional Cost = $60
This breakdown is more informative than simply seeing a $60 total because it shows where the cost comes from.
How Repayment Time Changes the Cost
One of the most useful calculations you can make is to compare different repayment periods.
Suppose you take a $500 cash advance with a 30% APR and a 5% fee.
The fee is:
$500 × 5% = $25
Now compare the estimated interest:
| Repayment Period | Estimated Interest* | Estimated Total Cost* |
|---|---|---|
| 10 days | $4.11 | $29.11 |
| 30 days | $12.33 | $37.33 |
| 60 days | $24.66 | $49.66 |
| 90 days | $36.99 | $61.99 |
*Simplified estimates using a 365-day calculation and assuming the full $500 balance remains outstanding.
The table demonstrates an important point: the cash advance fee may stay fixed while interest continues increasing with time.
This is why a person who expects to repay the balance quickly may get a very different result from someone who expects to carry it for several billing cycles.
Actual interest can differ because issuers use the calculation method described in the applicable card agreement.
What If You Can Repay the Cash Advance Quickly?
A short repayment period can reduce the amount of interest compared with carrying the balance longer, but it does not necessarily eliminate the cash advance fee.
For example, if a card charges 5% on a $1,000 cash advance:
$1,000 × 5% = $50
Even if the cash is repaid quickly, that $50 transaction fee may still apply under the card's terms.
This is why the calculator should be used before taking the cash advance, rather than only after the transaction has already occurred.
You can enter different repayment periods and see how the estimated interest changes.
What If You Need the Money for Several Months?
The longer a cash advance remains unpaid, the more important the interest calculation becomes.
Consider a hypothetical $1,000 cash advance:
- Cash advance fee: 5%
- Cash advance APR: 30%
- Estimated period: 90 days
The fee is:
$1,000 × 5% = $50
Simplified 90-day interest:
$1,000 × (30% ÷ 365) × 90 ≈ $73.97
Estimated additional cost:
$50 + $73.97 = $123.97
Estimated repayment:
$1,123.97
This does not mean every cardholder would receive exactly this result on a statement. It is a simplified illustration showing how quickly the financing cost can become meaningful when the balance remains outstanding.
For a longer repayment period, it becomes particularly important to check the card's actual APR, balance calculation method, payment terms, and any additional fees.
Cash Advance Limit vs. Available Credit
Another point to check before using a cash advance is your cash advance limit.
Your total credit limit and your cash advance limit are not necessarily the same.
For example, suppose a credit card has:
- Total credit limit: $10,000
- Available credit: $6,000
- Cash advance limit: $2,000
Having $6,000 of available credit does not necessarily mean you can withdraw $6,000 as cash.
Your card agreement may establish a separate cash advance limit.
The calculator estimates the cost of the amount you enter. It does not determine whether your issuer will approve that amount as a cash advance.
Always check your available cash advance limit before planning a withdrawal.
How Cash Advances Can Affect Credit Utilization
A cash advance uses part of your available credit, so it can increase your outstanding credit card balance.
For example, assume:
- Credit limit = $5,000
- Existing balance = $1,000
- Cash advance = $500
Your balance could increase to approximately $1,500 before considering additional charges.
A simple utilization calculation would be:
Credit Utilization = Credit Card Balance ÷ Credit Limit × 100
Therefore:
$1,500 ÷ $5,000 × 100 = 30%
The exact balance reported to the credit bureaus can depend on when the issuer reports your account and the balance at that time.
A cash advance itself is not normally reported as a separate "cash advance" mark on a credit report. However, the resulting balance can affect the reported utilization of the revolving account.
For people building or maintaining credit, this is another reason to consider the broader impact of increasing a credit card balance.
Cash Advance and Minimum Payments
Another issue is the relationship between a cash advance and your monthly payment.
Making only the minimum payment can allow a balance to remain outstanding for longer. When interest continues to accrue, the repayment period may become longer than expected.
Suppose a hypothetical cash advance produces a $500 balance plus applicable charges.
If the cardholder makes a very small payment each month, the balance may remain outstanding and continue generating interest according to the account terms.
The calculator's estimated cost based on a specific number of days should therefore be treated as a scenario, not a promise that the balance will be fully repaid by that date.
If you plan to make partial payments, a separate credit card payoff or debt repayment calculation may be more appropriate.
Common Mistakes When Calculating Cash Advance Fees
Even a simple calculation can go wrong if the wrong information is entered.
Using the Purchase APR
One of the most common mistakes is using the purchase APR instead of the cash advance APR.
Always check the cash advance section of your card agreement or statement.
Ignoring the Minimum Fee
If your card charges a percentage or a minimum dollar amount, whichever is greater, simply multiplying the withdrawal by the percentage may produce an incorrect fee.
For example:
$100 × 5% = $5
But if the minimum is $10:
Actual fee = $10
Forgetting ATM Charges
An ATM operator may charge a separate fee.
If your calculator allows an additional-fee input, include that amount.
Assuming Interest Starts Later
A normal purchase may qualify for a grace period, but cash advances generally do not receive the same treatment. The CFPB states that cash advance interest generally begins when the cash is withdrawn. (consumerfinance.gov)
Using the Wrong Number of Days
If you expect to repay after 15 days, entering 90 days can overstate the simple interest estimate. If you expect to carry the balance for 90 days but enter 15 days, the estimate can understate the potential interest.
Use a realistic repayment period.
Treating the Estimate as Your Exact Statement
A calculator is useful for planning, but your issuer's actual calculation controls the amount that appears on your statement.
Tips Before Taking a Credit Card Cash Advance
Before using your card for cash, review the following checklist:
- Check the cash advance APR.
- Check the cash advance fee.
- Check the minimum fee.
- Check your cash advance limit.
- Check for ATM charges.
- Estimate how long the balance will remain unpaid.
- Calculate the total estimated cost.
- Compare the cost with other available borrowing options.
- Check your card agreement for exact terms.
- Make sure the transaction is necessary and fits your repayment plan.
The purpose of this checklist is not to tell you which borrowing method to choose. It gives you the information needed to compare the actual cost of different options.
Cash Advance Calculator vs. Other Financial Calculators
Different calculators answer different questions.
| Calculator | Main Question |
|---|---|
| Cash Advance Fee Calculator | What could this credit card cash advance cost? |
| Credit Card Payoff Calculator | How long could it take to repay a credit card balance? |
| Credit Utilization Calculator | What percentage of my credit limit am I using? |
| Balance Transfer Calculator | Could transferring a balance change the estimated borrowing cost? |
| Loan Payment Calculator | What could a loan payment look like under given terms? |
Using the correct calculator matters because each tool is designed around a different financial calculation.
If your question is specifically about the cost of withdrawing cash from a credit card, the Credit Card Cash Advance Fee Calculator is the relevant starting point.
When a Cash Advance Calculator Is Most Useful
There are several situations where this calculator can provide useful information.
Before an Emergency Cash Withdrawal
If an unexpected expense leaves you considering a credit card cash advance, calculate the fee and estimated interest before withdrawing the money.
This lets you understand the potential cost before the transaction happens.
When Comparing Withdrawal Amounts
You can compare $100, $250, $500, and $1,000 withdrawals.
This is especially useful when your card has a minimum cash advance fee.
When Comparing Repayment Periods
Try 15, 30, 60, and 90 days.
Seeing the estimated interest for each period can make the cost of carrying the balance easier to understand.
When Checking a Credit Card Offer
If you are considering a card and want to understand its cash advance terms, you can use the disclosed fee and APR as inputs.
Remember that a card's purchase rewards or purchase APR do not automatically tell you whether its cash advance terms will be favorable for your particular situation.
A Practical Cash Advance Cost Checklist
Before using the calculator, collect these numbers from your credit card agreement or statement:
1. Cash advance amount
How much cash are you planning to withdraw?
2. Cash advance fee
What percentage does your card charge?
3. Minimum fee
Does the card specify a minimum dollar fee?
4. Cash advance APR
What APR applies specifically to cash advances?
5. Expected repayment period
How many days do you expect the balance to remain outstanding?
6. Additional fees
Will the ATM or another service charge an additional fee?
Once these numbers are available, enter them into the calculator.
Actionable Takeaways
Keep these points in mind when estimating the cost of a credit card cash advance:
- Do not look only at the cash advance fee.
- Check the cash advance APR separately from the purchase APR.
- Look for a minimum cash advance fee.
- Include ATM fees when applicable.
- Consider how long you expect to carry the balance.
- Use realistic numbers in the calculator.
- Compare several repayment scenarios.
- Check your cash advance limit before withdrawing money.
- Review your card agreement for exact terms.
- Treat calculator results as estimates rather than guaranteed statement amounts.
- Consider how the additional balance could affect credit utilization.
- Use other financial calculators when your question involves a different type of borrowing or repayment.
Frequently Asked Questions About Credit Card Cash Advance Fees
How is a credit card cash advance fee calculated?
A common percentage-based calculation is:
Cash Advance Fee = Cash Advance Amount × Fee Rate
If the card has a minimum fee, the applicable fee may instead be the greater of the percentage calculation and the minimum dollar amount. Always check your card's terms because fee structures vary.
How much does a $500 cash advance cost?
There is no single cost for every $500 cash advance. It depends on the card's cash advance fee, minimum fee, APR, repayment period, and any additional charges.
For example, at a hypothetical 5% fee, the initial cash advance fee would be:
$500 × 5% = $25
Interest and other fees would then be added according to the applicable terms.
Does a cash advance have interest?
Yes. Credit card cash advances generally accrue interest, and the CFPB states that interest generally begins when the cash is withdrawn. (consumerfinance.gov)
Is a cash advance fee the same as interest?
No.
The cash advance fee is a transaction-related charge. Interest is the financing charge that can accumulate while the balance remains outstanding.
Both can contribute to the total cost.
Does a cash advance affect my credit score?
A cash advance uses available revolving credit and can increase your credit card balance. A higher reported balance can increase your credit utilization, which is one factor considered in many credit scoring models.
The cash advance itself is not generally reported to credit bureaus as a separate negative account type.
Can I avoid a cash advance fee?
That depends on the card's terms and the transaction. Some cards may have different fee structures or promotional terms, while others charge a cash advance fee whenever a qualifying cash advance occurs.
Check your current card agreement before assuming a fee will not apply.
Does paying a cash advance immediately stop interest?
Paying the balance quickly can reduce the amount of interest that accumulates, but it does not necessarily eliminate a cash advance fee that was already charged.
The exact treatment depends on the card's terms.
What is the difference between a cash advance fee and an ATM fee?
A cash advance fee is charged by the credit card issuer under the card's terms. An ATM fee can be charged separately by the ATM operator or another service provider.
Both may contribute to the overall cost.
Final Thoughts
A credit card cash advance can provide access to cash quickly, but the amount you withdraw is not necessarily the full cost of the transaction. Cash advance fees, APR, repayment time, minimum fees, and ATM charges can all affect the final amount you pay.
The Credit Card Cash Advance Fee Calculator from iCreditCalculators provides a practical way to put these numbers together. By entering your actual card terms and testing different repayment periods, you can see how changes in the amount borrowed or the time outstanding affect the estimated cost.
The key is to use the calculator before making the transaction, not simply after the balance appears on your statement. Start with your actual cash advance terms, calculate the estimated fee and interest, review the total borrowing cost, and then compare that information with the other options available to you.
For the most accurate account-specific information, always confirm the current terms in your credit card agreement and statement. The CFPB's credit card resources can also help consumers understand common credit card terms and review issuer agreements. (consumerfinance.gov)
Use the Credit Card Cash Advance Fee Calculator from iCreditCalculators to turn a complicated cash advance calculation into a simple estimate you can understand and use for financial planning.
Sachin Ramdurg
Founder & Software Engineer
Sachin Ramdurg is the creator of iCreditCalculators.com. He brings over 15 years of software engineering expertise to build precision-engineered, privacy-first financial tools that empower consumers.